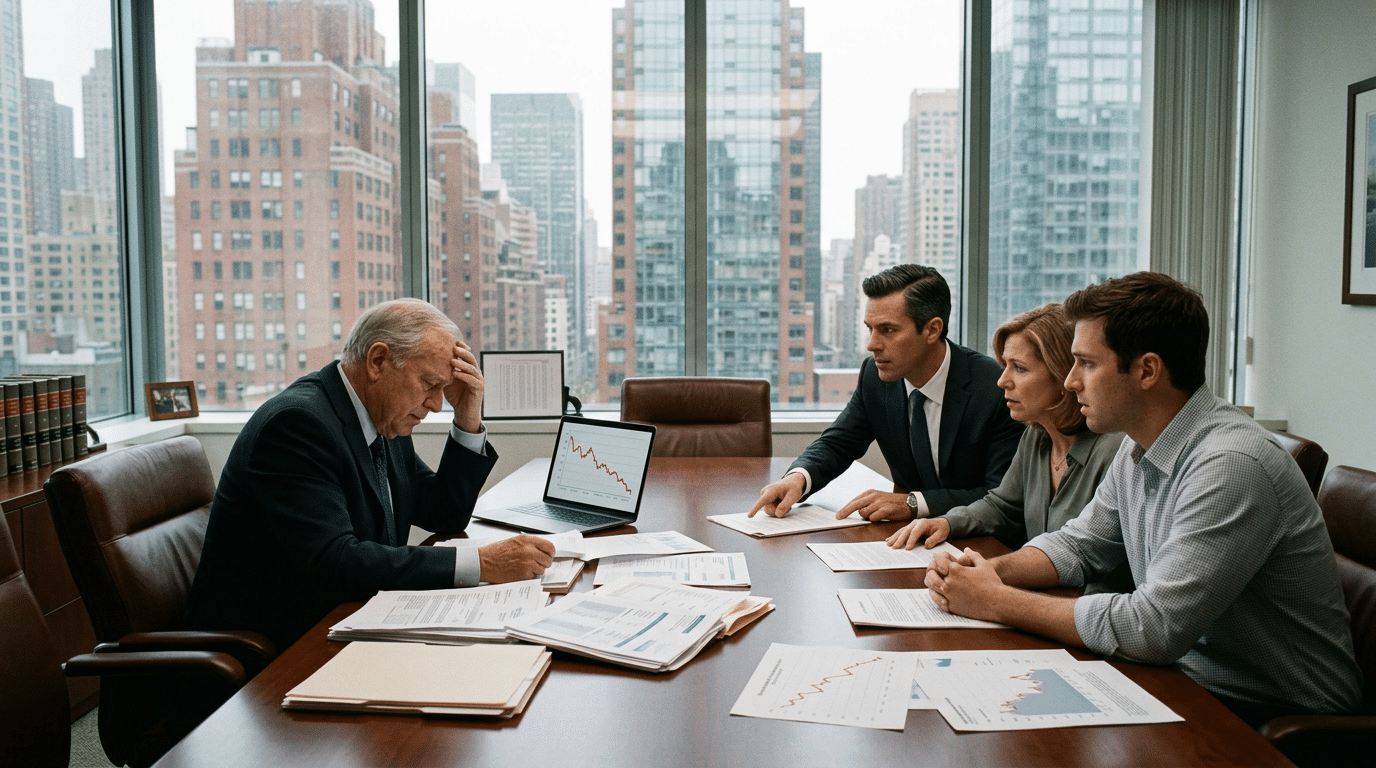
When someone agrees to serve as trustee of a New York trust, that person takes on more than an administrative role. A trustee may be responsible for managing investments, preserving trust assets, making distributions, keeping records, and balancing the interests of current and future beneficiaries. If investment decisions are careless, overly concentrated, self-interested, or inconsistent with the trust's purposes, beneficiaries may suffer substantial financial harm. We often remind clients that trustees are not judged solely by whether an investment made or lost money. New York law focuses heavily on the process the trustee used, the risks considered, and whether the trustee acted with the care, skill, and caution required of a fiduciary.
At Bernard Law P.C., we help families understand both sides of these disputes. A beneficiary may believe a trustee has mismanaged investments, while a trustee may need to defend decisions that were reasonable when made but later produced poor results. The distinction is important because a bad investment outcome does not automatically mean there was a breach of fiduciary duty.
New York Trustees Must Follow The Prudent Investor Rule
New York Estates, Powers and Trusts Law § 11-2.3 establishes the state's Prudent Investor Act. It requires a trustee to invest and manage trust property using reasonable care, skill, and caution and to evaluate investment decisions in the context of the entire portfolio. The law specifically recognizes that prudence is a standard of conduct rather than a guarantee of investment performance.
That means courts generally look at what the trustee knew at the time a decision was made, not simply whether an asset later increased or decreased in value. A trustee may make a reasonable decision that ultimately loses money because markets change. Conversely, an investment that happens to make money may still reflect poor fiduciary conduct if the trustee ignored obvious risks or acted for improper reasons.
The statute also requires trustees to consider matters such as liquidity needs, expected distributions, general economic conditions, tax consequences, inflation, the role of each asset within the portfolio, and the needs of beneficiaries. These obligations are especially important in long-term trusts where different beneficiaries may have different interests.
Failure To Diversify Can Create Serious Problems
One of the most common investment disputes involves concentration in a single asset or a small number of investments.
EPTL § 11-2.3 generally requires diversification unless the trustee reasonably determines that remaining concentrated is in the beneficiaries' interests.
A trust might, for example, receive a large block of stock in a family business or a publicly traded company. The trustee cannot simply assume that retaining the asset indefinitely is appropriate. The trustee should evaluate whether keeping that concentration fits the trust's objectives, distribution needs, tax considerations, and risk profile.
This does not mean every concentrated position must immediately be sold. A trust instrument may contain specific instructions, or tax and family considerations may support retaining certain assets. The critical issue is whether the trustee made an informed decision and documented the reasoning behind it.
Trustees Must Consider The Interests Of Different Beneficiaries
Investment management becomes more complicated when one group of beneficiaries receives current income while another group will receive the remaining principal later.
New York EPTL § 11-2.1 requires trust administration to take into account the respective interests of income beneficiaries and remaindermen.
A trustee should not structure investments solely to maximize current income if doing so threatens long-term preservation of principal. Likewise, investing exclusively for future growth while ignoring the legitimate needs of current beneficiaries may create problems.
The trustee's responsibility is to balance those interests in light of the trust's terms. This is one reason why trust investment management often requires more judgment than managing a personal portfolio. The trustee is managing someone else's property for multiple people who may have competing interests.
Delegating Investments Does Not Eliminate A Trustee's Responsibility
Trustees do not always have to select and manage investments personally. New York law permits delegation of investment and management functions when delegation is appropriate.
However, EPTL § 11-2.3 requires the trustee to exercise care, skill, and caution when selecting an investment manager, establishing the scope of the delegation, reviewing the manager's performance, and controlling costs.
Hiring a financial advisor therefore does not allow a trustee to stop paying attention. A trustee who hires someone and never reviews statements, fees, performance, or strategy may still face criticism.
Professional trustees and trustees who claim to possess particular investment skills may also be held to a higher level of diligence consistent with those represented skills.
A Trustee May Face A Surcharge For Investment Losses
When investment mismanagement causes measurable harm to a trust, beneficiaries may seek to hold the trustee financially responsible.
One possible remedy is a surcharge. A surcharge can require a trustee to restore money to the trust when losses resulted from a breach of fiduciary duty. The precise calculation may depend on what the trust would likely have been worth had the trustee acted properly.
The court may also examine whether excessive fees were paid, whether the trustee benefited personally from investment decisions, or whether improper transactions occurred.
An investment loss alone is not enough. A beneficiary generally must show that the trustee breached a fiduciary obligation and that the breach caused damage.
Removal Of A Trustee May Also Be Considered
Serious investment mismanagement can raise questions about whether the trustee should remain in control of the trust.
In some cases, beneficiaries may seek an accounting so they can examine investment transactions, fees, distributions, and other activity. New York law provides mechanisms for trustees and beneficiaries to address trust accountings and related relief. EPTL § 7-2.7, for example, addresses proceedings involving trustee accountings in Supreme Court.
Removal may become appropriate when misconduct is serious, ongoing, or demonstrates that the trustee can no longer administer the trust properly. The court's primary concern is protecting the trust and its beneficiaries.
A trustee facing these allegations should also take the matter seriously. Detailed records showing the reasoning behind investment decisions, professional advice obtained, portfolio reviews, and communications with beneficiaries can become critically important.
Trust Investment Disputes Require More Than Looking At Returns
The central question in a trust investment dispute is rarely whether the portfolio beat the market. New York's Prudent Investor Act focuses on the trustee's decision-making process, the trust's purposes, diversification, risk and return objectives, beneficiary needs, and the portfolio as a whole.
We encourage beneficiaries who see unexplained losses, excessive concentration, unusual trading, high fees, or apparent conflicts of interest to obtain a clear understanding of what occurred. We likewise encourage trustees to treat investment management as an ongoing fiduciary responsibility rather than a passive task.
New York Trustee Frequently Asked Questions
Is A Trustee Personally Liable Every Time A Trust Investment Loses Money?
No. New York's Prudent Investor Act makes clear that prudence is judged by the trustee's conduct, not simply the result. A trustee may make a reasonable investment decision that later loses money because of market conditions. Liability becomes more likely when losses are connected to imprudent decision-making, failure to diversify, conflicts of interest, or other fiduciary breaches.
Does A Trustee Have To Diversify Every Trust Portfolio?
Generally, a trustee should diversify unless there is a reasonable basis for not doing so. EPTL § 11-2.3 specifically identifies diversification as part of the prudent investor standard. A trust may justify retaining a concentrated asset in some circumstances, but the trustee should evaluate the risks and document the reasons for that decision.
Can A Trustee Hire A Financial Advisor To Manage Trust Investments?
Yes. New York law permits trustees to delegate investment functions when appropriate. The trustee still has responsibilities when selecting the advisor, establishing the terms of the delegation, reviewing performance, and monitoring costs. Delegation does not mean the trustee can simply stop supervising the trust's investments.
What Can A Beneficiary Do If The Trust Has Suffered Large Investment Losses?
A beneficiary may request information, review trust statements, seek an accounting, and potentially pursue legal relief if there is evidence of fiduciary misconduct. Depending on the circumstances, remedies may include restoration of losses, repayment of improper expenses, or removal of the trustee.
What Is A Trustee Surcharge?
A surcharge is a financial remedy that can require a trustee to reimburse a trust for losses caused by a breach of fiduciary duty. The issue is not simply how much the portfolio declined, but whether improper conduct caused the loss.
Can A Trustee Favor Current Beneficiaries Over Future Beneficiaries?
A trustee generally must consider both. New York law requires due regard for the respective interests of income beneficiaries and those who will ultimately receive principal. Investment decisions that unfairly favor one group may create fiduciary concerns.
Schedule A Free Consultation With Bernard Law P.C.
Trust administration requires careful judgment, particularly when significant investment assets are involved. When a trustee fails to diversify, ignores beneficiary needs, pays unreasonable investment expenses, or makes decisions inconsistent with the trust's purposes, the financial consequences can be substantial.
At Bernard Law P.C., we assist trustees, beneficiaries, and families with trust planning, trust administration, fiduciary issues, estate planning, and related disputes. Our goal is to help clients understand what the trust requires, what New York fiduciary law expects, and what options may be available when investment management becomes a concern.
If you are concerned that a trustee has mismanaged trust investments, or if you are serving as trustee and need guidance regarding your fiduciary responsibilities, Bernard Law P.C. can help. Our law office is located in Shoreham, New York, and we serve clients throughout Suffolk County.
Call Bernard Law P.C. at (631) 378-2500 to schedule a free consultation and discuss your trust, estate planning, or fiduciary concerns.