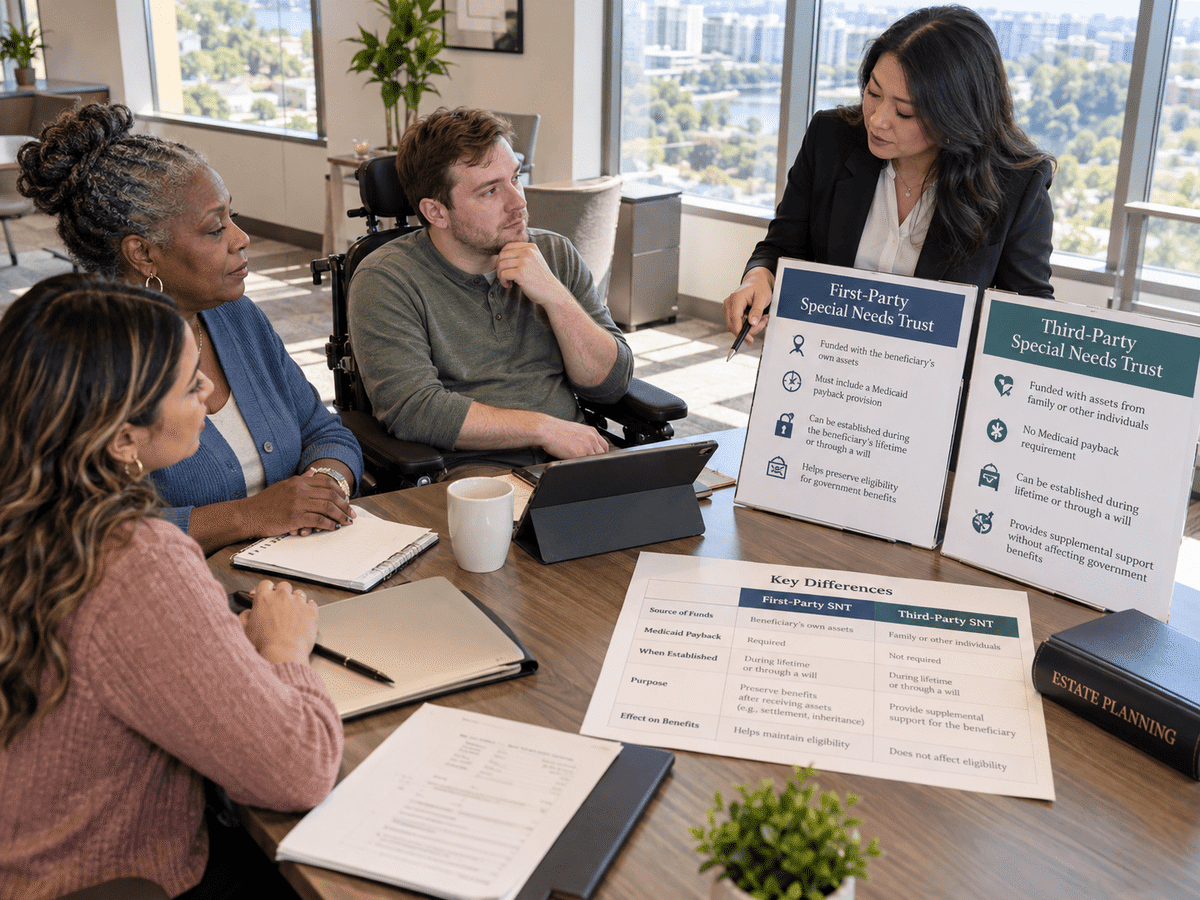
When families plan for a loved one with a disability, they often want to make sure financial support does not put government benefits at risk. A special needs trust, sometimes called a supplemental needs trust in New York, can help achieve this. Not all special needs trusts are the same, though. A key difference is whether the trust uses the beneficiary’s own money or someone else’s assets. This choice affects how the trust is set up, what rules apply, and what happens to any money left after the beneficiary passes away.
At Bernard Law P.C., we explain to families in Suffolk County that special needs planning involves more than just putting money into a trust. Where the money comes from is important. Both first-party and third-party special needs trusts can help during the beneficiary’s life, but they may have very different effects on the family.
New York Law Protects Supplemental Needs Trusts
New York Estates, Powers and Trusts Law § 7-1.12 establishes the state’s framework for supplemental needs trusts for individuals with severe and chronic or persistent disabilities. The statute is designed to allow trust assets to supplement rather than replace government benefits.
A well-designed trust usually lets the trustee decide how to distribute funds. The beneficiary should not be able to take money from the trust whenever they want, because having direct access could make those assets count as resources for programs like Supplemental Security Income or Medicaid.
The main idea is simple. The trust can make life better for the beneficiary and still allow them to get government help if the rules are followed. Whether the trust uses the beneficiary’s own money or someone else’s makes a big difference in how this works.
What Is A First-Party Special Needs Trust?
A first-party special needs trust uses money that belongs to the person with the disability. This money might come from a personal injury settlement, an inheritance received directly, savings, back payments from government benefits, or other assets the beneficiary owns.
New York Social Services Law § 366(2)(b)(2)(iii) recognizes certain trusts funded with the assets of a disabled individual and allows those assets to be excluded from Medicaid resource calculations when the statutory requirements are satisfied. Federal law also governs these trusts under 42 U.S.C. § 1396p(d)(4).
A key feature of a first-party trust is that it must repay Medicaid. When the beneficiary dies, any money left in the trust usually has to go to the state to pay back Medicaid for benefits provided, as required by law.
This rule can greatly affect what is left for the family. Families might think that any leftover money will go to siblings or other heirs, but Medicaid repayment comes first.
How A Third-Party Special Needs Trust Is Different
A third-party special needs trust is funded with assets belonging to someone other than the beneficiary. Parents, grandparents, siblings, or other relatives may establish or fund the trust as part of their own estate planning.
For example, instead of leaving $300,000 directly to an adult child who gets means-tested benefits, parents can put that inheritance into a well-prepared third-party supplemental needs trust. The trustee can then use the money to improve the child’s life while keeping their benefits, as allowed by the rules.
The biggest difference is what happens when the beneficiary dies. Unlike a first-party trust, a properly set up third-party trust usually does not have to pay back Medicaid just because the beneficiary received benefits.
The person creating the trust can therefore determine who receives the remaining assets. The trust might provide that unused funds pass to the beneficiary’s siblings, nieces and nephews, charities, or other beneficiaries.
That distinction is one of the strongest reasons families should plan before an inheritance is received rather than attempting to correct the problem afterward.
Leaving An Inheritance Directly Can Create Problems
One of the most damaging estate planning mistakes occurs when a parent leaves assets directly to a child who relies on SSI, Medicaid, or another means-tested program.
An outright inheritance can increase the beneficiary’s countable resources and potentially interfere with eligibility. Once the beneficiary legally owns the inheritance, the planning options may become more limited. A first-party trust may sometimes be used to preserve eligibility, but the Medicaid repayment requirement can then become part of the arrangement.
By contrast, establishing a third-party supplemental needs trust before the inheritance passes may allow the family’s assets to remain protected for the beneficiary’s supplemental needs without converting those family assets into a first-party trust.
This is why beneficiary designations require careful attention. A well-drafted trust can be undermined if a parent names the child directly on a retirement account, life insurance policy, or payable-on-death account.
The Trustee’s Decisions Matter
Creating the right trust is only part of the planning process. Selecting the right trustee is equally important.
Under EPTL § 7-1.12, the trust is intended to supplement government assistance rather than simply replace benefits that would otherwise be available. The trustee therefore needs to understand how different distributions may affect the beneficiary.
Payments for education, transportation, recreation, therapies, technology, personal services, and other supplemental needs may be handled differently from distributions involving cash, food, or shelter. Poorly planned distributions may reduce or disrupt benefits even when the trust itself was drafted correctly.
For that reason, we encourage families to select a trustee who is reliable, financially responsible, and willing to understand the rules governing the beneficiary’s particular benefits.
New York And Florida Families Should Coordinate Their Planning
Families who divide their time between New York and Florida should review special needs planning carefully when residency or family circumstances change. Both states operate within federal Medicaid and Social Security rules, but state administration and trust law can differ.
If a beneficiary moves from New York to Florida, or if parents establish a trust while living in one state and later relocate to the other, the trust should be reviewed to determine whether it continues to accomplish its intended purpose.
The broader lesson is that special needs planning should be coordinated with the family’s entire estate plan. Wills, trusts, retirement accounts, life insurance policies, and beneficiary designations should all direct assets consistently.
For many families, the difference between a first-party and third-party special needs trust ultimately comes down to timing. Planning before assets pass to the person with the disability often provides significantly greater flexibility.
New York Special Needs Trusts Frequently Asked Questions
What Is The Main Difference Between A First-Party And Third-Party Special Needs Trust?
The primary difference is who owns the assets used to fund the trust. A first-party trust contains assets belonging to the beneficiary, while a third-party trust contains assets contributed by parents, grandparents, or other people. That distinction also affects what happens at the beneficiary’s death.
Does A First-Party Special Needs Trust Have To Repay Medicaid?
Generally, yes. A qualifying first-party trust established under the applicable Medicaid rules must provide for repayment to the state or states for Medicaid assistance paid on behalf of the beneficiary, subject to the applicable statutory requirements and available trust assets.
Does A Third-Party Special Needs Trust Have To Repay Medicaid?
Generally, a properly drafted third-party trust funded exclusively with someone else’s assets does not have the same Medicaid repayment requirement. The person creating the trust can usually designate remainder beneficiaries who receive the assets after the disabled beneficiary dies.
Can Parents Leave An Inheritance Directly To A Child With A Disability?
They can, but doing so may cause problems if the child receives means-tested benefits such as SSI or Medicaid. An outright inheritance can become a countable resource. Directing the inheritance into a properly structured third-party supplemental needs trust may provide greater protection.
Can A Special Needs Trust Pay For Anything The Beneficiary Wants?
Not necessarily. The trustee must consider how distributions affect government benefits. Some purchases and payments may have little or no effect, while others may reduce benefits or create eligibility issues. Trustee discretion and proper administration are therefore very important.
Can A Personal Injury Settlement Go Into A Special Needs Trust?
Potentially, yes. Because settlement proceeds belong to the injured beneficiary, the trust would generally be treated as a first-party special needs trust if the required legal conditions are satisfied. Medicaid repayment requirements may therefore apply at the beneficiary’s death.
What Happens If A Parent Already Left Money Directly To A Disabled Child?
The available options depend on the circumstances. In some cases, a first-party special needs trust or pooled trust may help preserve eligibility. However, families generally have more flexibility when planning occurs before assets are transferred directly to the beneficiary.
Call Our Special Needs And Estate Planning In Shoreham For A Free Consultation
Special needs planning requires more than simply creating a trust. Families need to determine where the assets will come from, which benefits need protection, who should serve as trustee, and what should happen to remaining property after the beneficiary’s death. At Bernard Law P.C., we help families create estate plans that address these questions while protecting the long-term interests of loved ones with disabilities.
If you are considering a first-party or third-party special needs trust, or you want to make sure an inheritance will not unintentionally interfere with a loved one’s government benefits, Bernard Law P.C. can help. Our law office is located in Shoreham, New York, and we serve clients throughout Suffolk County. Contact our Suffolk County estate lawyer at Bernard Law P.C. by calling (631) 378-2500 to schedule a free consultation.